Key points
“No tax on overtime” does not make overtime tax-free. The One Big Beautiful Bill Act gives eligible workers an income tax deduction for qualified overtime compensation and qualified tips for tax years 2025 through 2028. No tax on overtime W-2 reporting becomes mandatory with the 2026 Form W-2, which is due to employees by February 1, 2027, so employers must now report qualified overtime and tips separately.
For tax year 2025, separate reporting was voluntary. Notice 2025-62 waived penalties for employers that did not separately report cash tips, tipped occupations or qualified overtime on 2025 forms, as long as the rest of the return was complete and correct. The 2025 Form W-2 was never redesigned for the new deductions.
That relief does not carry into 2026. The IRS has issued the final 2026 Form W-2 and the 2026 General Instructions for Forms W-2 and W-3. They add three box 12 codes and split box 14 into two boxes. In Fact Sheet FS-2026-13 (August 2026), the IRS says an employee can deduct only the qualified overtime that the employer reports on a properly furnished Form W-2, and that no relief from that rule applies after 2025. A missing or low code TT amount therefore costs the employee part of the deduction, and the employer can face information-return penalties. Code TT is one item on a longer year-end list; the year-end payroll checklist covers the rest.
No. Overtime and tips are still wages. They stay in box 1 and remain subject to federal income tax withholding, Social Security tax, Medicare tax and FUTA, just as before. The deduction is claimed by the employee on Schedule 1-A of Form 1040, and only for a portion of the pay. Payments to independent contractors are not wages: they go on Form 1099-NEC, never carry a code TT amount, and the 1099 threshold for 2026 has changed too.
The limits that apply on the employee’s return are:
The employer does not apply any of these caps. If an employee earned $30,000 of qualified overtime, the full $30,000 goes in box 12 with code TT, even though the deduction tops out at $12,500 (FS-2026-13, Q10).
Payroll also cannot reduce income tax withholding on its own initiative. Under FS-2026-13 (Q8), withholding changes only when the employee files a new Form W-4 claiming the expected deduction in Step 4(b) of the 2026 form.
Qualified overtime compensation is the part of overtime pay that section 7 of the Fair Labor Standards Act requires above the employee’s regular rate. Under ordinary time-and-a-half, that is the “half.” The full 1.5 times rate is not qualified.
Some overtime does not qualify at all:
Employees properly classified as exempt have no FLSA-required overtime to report, so check the FLSA exempt salary threshold and duties tests rather than relying on a job title.
The IRS’s basic weekly formula is:
FLSA hours over 40 in the workweek × one-half × the employee’s FLSA regular rate = qualified overtime for that week.
To build the code TT amount for each employee:
| Scenario ($20/hour base rate) | Overtime paid | Code TT amount |
|---|---|---|
| 50 hours in the workweek, paid time-and-a-half | 10 hours × $30 = $300 | $100 (10 × $10) |
| 50 hours in the workweek, paid double time | 10 hours × $40 = $400 | $100 (only the FLSA-required half) |
| 45 hours at $20/hour plus a $100 nondiscretionary weekly production bonus | Regular rate = ($900 + $100) ÷ 45 hours = $22.22; half-time premium for 5 hours = $55.56 | $55.56 (5 × $11.11) |
| Two 10-hour days, 38 hours total, state daily overtime paid | 4 hours × $30 = $120 | $0 (the FLSA requires no overtime under 40 hours) |
| Exempt manager paid overtime under a union contract | Any amount | $0 (not FLSA overtime-eligible) |
The double-time row comes from the IRS’s own example in FS-2026-13 (Q16). When a week mixes state daily overtime with more than 40 hours, apply FLSA sections 7(e) and 7(h) to find the amount the FLSA required, and report only that. Hospitals using the 8/80 system and public employers using section 7(k) or 7(o) compensatory time follow special rules: FAQs 17 and 18 cover them, including when comp time counts as paid.
Qualified tips are voluntary cash or charged tips, including tips received through a tip-sharing arrangement, in an occupation on the Treasury list of jobs that customarily and regularly received tips on or before December 31, 2024. Mandatory service charges and automatic gratuities are not tips. The final regulations (T.D. 10044, published April 13, 2026) made the occupation list final and exhaustive. They also exclude tips received in a specified service trade or business and tip-pool amounts paid to managers or supervisors.
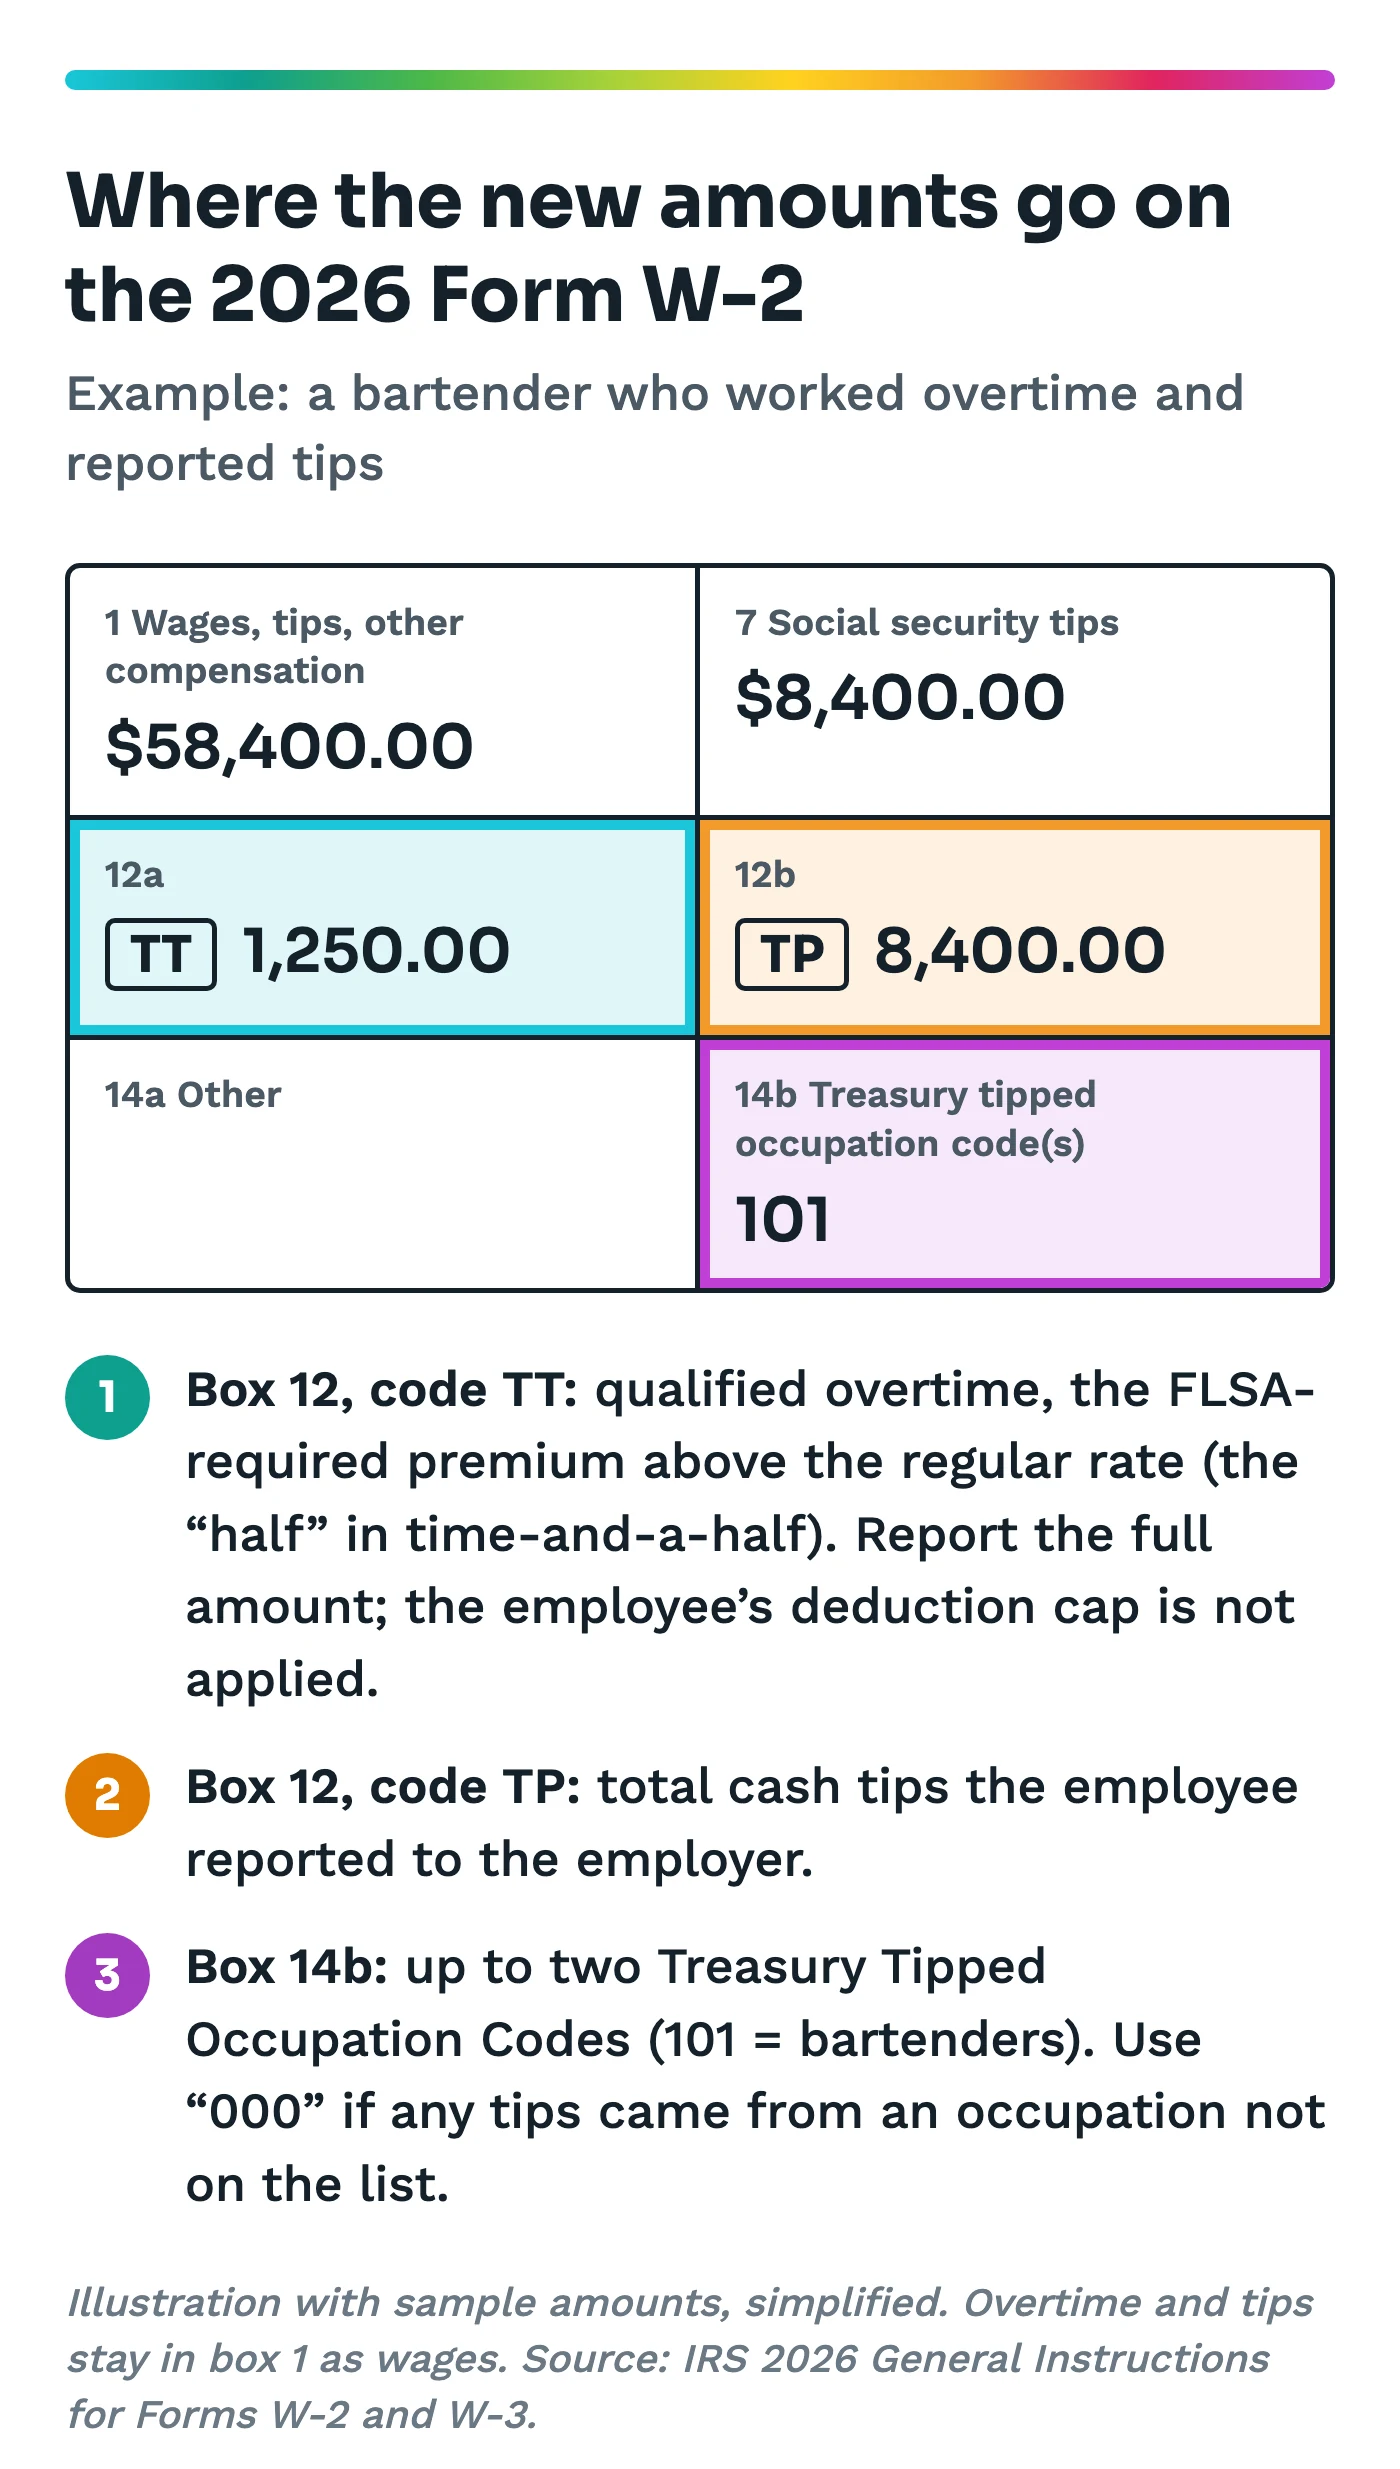
The employer’s W-2 job is narrower than deciding whether each tip is qualified. Box 12 code TP reports the total cash tips the employee reported to the employer. Box 14b reports the occupation code. The Treasury Tipped Occupation Codes are three-digit numbers, such as 101 for bartenders and 102 for wait staff. The 2026 instructions set these rules for box 14b:
Tips of $20 or more in a month remain subject to income tax withholding, Social Security tax and Medicare tax, as before.
| Item | What to report | Where on the 2026 W-2 | Source |
|---|---|---|---|
| All wages, including overtime and tips | Full taxable amounts, as before | Boxes 1, 3, 5 and 7 (Social Security tips) | 2026 W-2/W-3 instructions |
| Qualified overtime compensation | Total FLSA-required premium above the regular rate, with no cap applied | Box 12, code TT | W-2/W-3 instructions; FS-2026-13 Q10 |
| Cash tips | Total cash and charged tips the employee reported to the employer | Box 12, code TP | W-2/W-3 instructions |
| Tipped occupation | Up to two Treasury Tipped Occupation Codes; “000” if any tips came from an unlisted occupation | Box 14b | W-2/W-3 instructions |
| Employer Trump account contributions | Contributions under a section 128 program (permitted from July 4, 2026) | Box 12, code TA | W-2/W-3 instructions |
| Items formerly in box 14 “Other” | Same items as before | Box 14a | W-2/W-3 instructions |
| Errors in TT, TP or box 14b | Corrected amounts or codes | Form W-2c (box 12 or box 14b) | FS-2026-13 Q11; W-2c instructions |
Paper filers should check box 12 capacity. Copy A of a paper Form W-2 holds only four box 12 entries. An employee with codes DD, D, W, TT and TP needs a second Form W-2, and the second form counts toward the 10-return e-file threshold. The rare worker who is an employee under the FLSA but an independent contractor for tax purposes gets qualified overtime reported on Form 1099-NEC, box 1d, or Form 1099-MISC, box 14.
Correct it with Form W-2c. Under FS-2026-13 (Q11), an employer that finds an error in box 12 code TT must file Form W-2c with the SSA and give a copy to the employee as soon as possible. The 2026 instructions provide for box 14b corrections on Form W-2c the same way. File the W-2c electronically if the original W-2 was e-filed.
Employees have no workaround if the employer leaves an amount off. They cannot deduct qualified overtime that is missing from box 12 code TT, and Form 4852 (the substitute W-2) does not count, so a corrected W-2c is their only route (Q20–Q23). An overstated amount does not help them either, because they can deduct only what was actually paid. Expect W-2c requests from employees in February through April 2027.
Penalties apply too. For returns due after December 31, 2026, the penalty for failing to file a correct Form W-2 reaches $340 per form, with lower amounts for corrections filed soon after the deadline. Intentional disregard carries at least $690 per form.
January 31, 2027 is a Sunday, so 2026 Forms W-2 are due to employees and to the SSA by February 1, 2027. Steps to take before then: January is also when many states raise pay floors, so check minimum wage 2027 by state while you update rates.
If your team needs a refresher on how regular rate, hours worked and exemptions are determined, the live FLSA wage and hour compliance webinar covers the rules that drive the code TT calculation. Other payroll and tax sessions are listed under payroll and taxation webinars.
No. Overtime is still wages subject to income tax withholding, Social Security and Medicare tax. Eligible employees can deduct up to $12,500 ($25,000 joint) of the FLSA-required premium portion on their 2025–2028 returns, and the deduction phases out above $150,000 of modified AGI ($300,000 joint).
For each workweek, multiply the hours worked over 40 by one-half of the employee’s FLSA regular rate, which includes nondiscretionary bonuses and shift differentials. Add the weekly amounts for the year and report the total in box 12 with code TT. Double time and state-only overtime count only to the extent the FLSA required them.
Code TT is new on the 2026 Form W-2 and reports the total qualified overtime compensation paid during the year. That is the FLSA-required amount above the regular rate, usually the “half” in time-and-a-half. Employers report the full amount even if it exceeds the employee’s deduction cap.
Only to the extent the FLSA also required it. Overtime paid solely because of a state daily-overtime rule, a union contract or company policy is not qualified overtime. When a week includes both, the employer reports only the premium the FLSA required.
Box 14b holds up to two three-digit Treasury Tipped Occupation Codes for an employee whose cash tips are reported in box 12 with code TP. If any tips came from an occupation that is not on the IRS list, one of the codes must be “000.”
Ask the employer for a Form W-2c that reports the correct code TT amount. For 2026 and later, the IRS says employees cannot deduct qualified overtime that is not reported on a W-2 or W-2c, and a substitute Form 4852 does not qualify.
No. Notice 2025-62 made 2025 a transition year with penalty relief, and employers could report the amounts voluntarily in box 14, on a separate statement or through an online portal. Mandatory reporting starts with the 2026 Form W-2.
Get payroll ready before W-2 season
The FLSA wage and hour webinar explains the regular rate, hours worked and exemptions behind every code TT amount. Book one seat or the whole payroll team.
See the FLSA webinarThis article is general information, not legal or tax advice. Check the official sources above or consult a qualified advisor for your situation.
I-9 Audit Checklist: How to Self-Audit Before ICE Does
Nacha Fraud Monitoring Rules 2026: Phase 1 and Phase 2
FDA Compliance
Medical Devices
Clinical Research
Audit Webinar
HR Compliance
Banking and Finance
Hospital and Healthcare
Packaging and Labeling
Accounting, Payroll and Taxation
Food and beverages
Software
Miscellaneous
Pharmaceutical